
It’s been a chaotic week across the dealmaking world. From Manhattan trading floors to sleepy British high streets and sun-drenched golf greens, the capital is moving in big, noisy ways.
Three major stories tell the tale of where money is migrating right now: Citigroup fighting tooth and nail to keep its top dealmakers from bolting to private equity, a billionaire Canadian dynasty stepping in to rescue Britain’s favorite chemist, and Saudi Arabia writing another massive check to keep LIV Golf swinging.
Wall Street's Talent Drain: Why Citi Bankers Are Packing Bags for PE
At Citigroup, CEO Jane Fraser has spent the last year carrying out a brutal, sweeping corporate overhaul—slashing bureaucracy, flattening management layers, and trying to get the sprawling bank into fighting shape.
Now, she's running into an expensive new problem: her best dealmakers are being poached.
Private equity giants and booming private credit shops like Blackstone, Ares, and Apollo are aggressively raiding Wall Street desks for talent. And frankly, it’s an unfair fight. Private equity shops can offer uncapped performance fees ("carried interest") and dizzying paydays that traditional publicly traded banks simply can’t match under today's tight regulatory caps and shareholder scrutiny.
For Citi, the exodus couldn't happen at a worse time. If Fraser wants to revive the bank's M&A advisory business and boost returns, she needs seasoned rainmakers who can actually bring multibillion-dollar corporate mergers in the door. In response, bank leadership is scrambling—sweetening deferred stock bonuses and dangling bigger client portfolios to keep senior managing directors from jumping across the street.
The lesson is simple: Wall Street's biggest threat isn’t Goldman Sachs or JPMorgan anymore. Its private capital funds flush with trillions in dry powder, ready to buy anyone with a Rolodex.
A Canadian Dynasty Steps In to Fix Boots
Across the pond, one of Britain's most storied brands just found a way out of corporate purgatory.
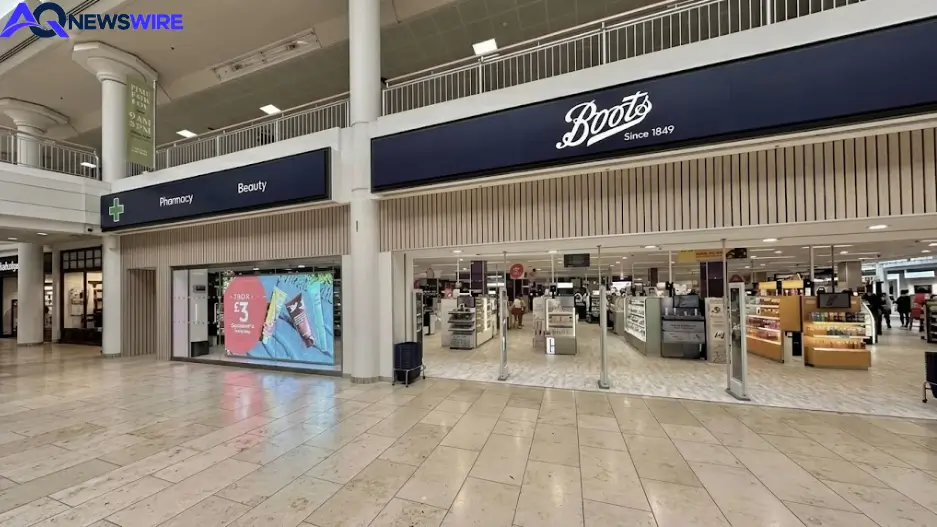
The billionaire Weston family—the retail royals behind Canada’s Loblaw supermarket chain and Shoppers Drug Mart—inked an $8.9 billion (£6.7 billion) buyout to take Boots off Walgreens’ hands.
For the British public, the deal brings an end to a depressing decade under American stewardship. Since Walgreens took over in 2014, Boots stores have visibly deteriorated. Aisles got tired, checkouts grew painfully slow, and the chain looked like an afterthought while Chicago executives worried about their struggling US balance sheet.
The Westons, on the other hand, know this exact playbook. They ran Shoppers Drug Mart in Canada by nailing three basic things:
Turning pharmacies into community healthcare hubs where people can get vaccinated or treated for minor illnesses without waiting weeks for an appointment.
Upgrading tired store layouts to make grabbing a sandwich or toiletries frictionless.
Pouring resources into the lucrative, beloved No7 skincare brand to sell it on the global stage.
Backed by a massive loan package led by CIBC and Morgan Stanley, the takeover proves that brick-and-mortar retail isn't dead—it just needs owners who actually care about the shops they own.
Saudi Money Keeps the LIV Golf Dream Alive
Meanwhile, in the sports world, anyone waiting for LIV Golf to run out of cash is going to be waiting a very long time.
Despite two years of agonizing talks about merging with the PGA Tour, negotiations remain hopelessly bogged down in antitrust inquiries, congressional hearings, and boardroom politics. Rather than waiting around, Saudi Arabia’s Public Investment Fund (PIF) just injected another massive cash injection into LIV to guarantee its tournament calendar, hefty player paychecks, and broadcast operations through the coming seasons.
By all traditional business logic, LIV should be hurting. It has burned billions of dollars, television viewership remains modest, and corporate sponsors have been slow to jump on board.
None of that matters when your backer has sovereign-wealth-sized pockets. By extending LIV’s financial runway, the Saudis are sending a crystal-clear message to the PGA Tour and federal regulators: We aren't going anywhere.
If a permanent peace deal ever gets signed in men’s professional golf, it won’t happen because LIV ran out of money—it will happen on terms that give Riyadh a permanent seat at the table.