
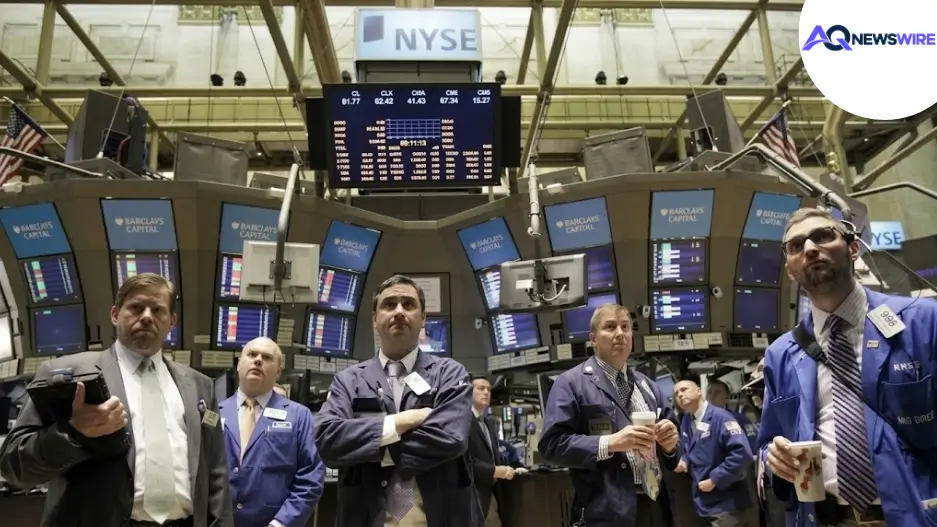
U.S. equity futures traded with sharp divergence ahead of the opening bell on Tuesday morning as investors digested the unofficial kickoff of third-quarter corporate earnings. Major benchmark contracts reflected a clear sector rotation: the Dow Jones Industrial Average pointed significantly higher, propelled by healthcare and financial heavyweights, while tech-heavy Nasdaq futures slid under heavy selling pressure across semiconductor and hardware supply chains.
The morning trading session highlights a market attempting to calibrate competing crosscurrents. Strong quarterly reports and raised corporate forecasts among defensive blue chips provided a stabilizing buffer, even as profit-taking and competitive warnings triggered a steep retreat across hardware and memory hardware names.
Healthcare Strength Lifts Early Sentiment
Leading the premarket gainers among mega-cap constituents, UnitedHealth Group (UNH) climbed more than 3% following an upbeat third-quarter earnings report. The healthcare and managed-care giant topped Wall Street expectations across top and bottom lines, posting adjusted earnings per share of $4.69 on consolidated revenue surpassing $112.6 billion.
More importantly for market sentiment, UnitedHealth raised its full-year 2026 earnings guidance. Executives cited steady operating cash generation and disciplined medical loss ratios as key drivers of operational margin improvement. The upbeat guidance triggered sympathetic buying across broader managed care and healthcare providers, helping anchor the Dow firmly in positive territory prior to the opening bell.
Banking Giants Set Mixed Tone for Earnings Season
The kickoff of third-quarter reports from America’s premier financial institutions produced active, two-way trading across banking desks:
JPMorgan Chase (JPM): Shares of the nation's largest lender swung between modest declines and mild gains, advancing roughly 1% to 1.5% in early trade. While the bank delivered substantial profitability driven by solid investment banking and trading fee activity, top-line revenue of $50.91 billion narrowly missed consensus forecasts of $51.22 billion. Chief Executive Jamie Dimon reiterated a measured macro outlook, noting that while the domestic economy remains resilient, geopolitical risks and fiscal deficits require disciplined balance-sheet management.
Goldman Sachs (GS): Investment banking peer Goldman Sachs surged over 3.4% premarket after blowing past consensus expectations. The Wall Street powerhouse logged quarterly earnings of $17.01 per share against the $13.09 projected by analysts, lifted by a 23% annual jump in global banking and market revenues.
Wells Fargo (WFC): In contrast, Wells Fargo dropped more than 1% to 3% premarket. Although lending margins held steady, revenue of $21.87 billion trailed street forecasts, marking the bank’s third top-line miss over the past four quarters and weighing on consumer banking sentiment.
Memory Chips and Hardware Face Sharp Global Headwinds
While healthcare and select financials posted gains, the technology sector came under severe pressure, driven by an acute slump across memory chips and storage providers.
Micron Technology (MU) dropped between 4% and 5.5% in premarket trade, leading broader semiconductor losses. The slide followed a bruising overnight session across Asian equity markets, where South Korean technology indexes tumbled amid mounting concerns over memory pricing dynamics, softening PC replacement cycles, and intensifying supply competition from Chinese state-backed fabricators.
The downward momentum cascaded across the data storage complex. Storage hardware peers Western Digital (WDC) and Seagate Technology (STX) both slid sharply, tumbling between 7% and 8.4% before the opening bell. Heavyweight semiconductor names, including AMD, Marvell Technology, and Nvidia, also traded in the red, dragging down overall tech multiples.
Macro Context: Yields Soften Ahead of Inflation Print
Providing an underlying cushion for risk assets, benchmark 10-year Treasury yields retreated slightly from their recent highs. Comments from Federal Reserve officials indicated that higher long-term borrowing costs have already begun curbing demand in rate-sensitive sectors, reducing the urgency for immediate additional monetary tightening.
Crude oil benchmarks also eased slightly, lowering energy input pressures for domestic corporations. Nevertheless, institutional traders remain cautious ahead of tomorrow's Consumer Price Index (CPI) release, which will serve as the primary litmus test for the Federal Reserve’s upcoming policy trajectory.
As the opening bell approaches, the split tape highlights an earnings season where headline beats alone are insufficient: investors are demanding flawless execution, cost discipline, and robust forward-looking guidance to reward equity valuations.